Downsizing Realtor Austin

Four paths through the concurrent sale and purchase

Every Austin downsize is really two coordinated transactions: sell the current home, buy the next one. The order you run them in and the timing you negotiate decide whether you end up in short-term housing, holding two mortgages, or hitting it clean.

By Luke Allen · TREC #788149 · Updated October 12, 2026

Pick the right path
Four paths, each with its own tradeoff

Pick the path that matches your risk tolerance

Each path works for a different Austin downsizer profile. The right path depends on equity position, financing comfort, timing flexibility, and risk tolerance.

1
Lowest cost, most friction

Sell first, buy second

List current home, close the sale, deposit proceeds, shop for new home from a cash position. Avoids any double-mortgage exposure or bridge-loan cost. Typically requires a short-term rental, family stay, or storage window between closings.

Works for:Downsizers with flexible timing, access to short-term housing (family, friends, short-term rental), and preference for the simplest financial structure.
Risk:15-30 days of transitional living. Shopping under pressure if the new-home market moves while you are between homes.
2
Highest cost, lowest friction

Buy first with bridge financing

Secure the new home using bridge financing against current-home equity. Move at a comfortable pace. List and sell the current home from a non-pressured position. Pay off the bridge loan at the current-home closing.

Works for:Downsizers with substantial current-home equity (ideally low or no mortgage), tolerance for carrying cost, and preference for a comfortable move.
Risk:Bridge-loan interest cost (typically 1-2% monthly on a 6-12 month facility). Market risk on the current home sale while bridge is outstanding.
3
Precise, highest coordination

Concurrent close

Time listing of current home, offer acceptance on new home, and closing dates so both transactions close on the same day. Proceeds from the sale flow directly into the purchase closing. No short-term housing and no bridge cost.

Works for:Downsizers in a cooperative market where both sides can commit to the specific coordinated date, and realtor team disciplined on timing.
Risk:Minor delay on either side cascades into both transactions. Requires precise execution.
4
Simple, less competitive

Contingent purchase

Make the new-home purchase offer contingent on the current home selling. Clean structure that aligns transaction timing automatically. Limits new-home choices to sellers who will accept contingencies.

Works for:Downsizers in markets with limited competition for the new-home target where seller is willing to accept contingency, and where the current home will clearly sell.
Risk:Weaker competitive position in multiple-offer scenarios. Many sellers reject contingent offers outright.
What the equity rollover actually looks like

A worked Austin downsize example

Long-tenure Westlake owner downsizing to Sun City Georgetown. Illustrative numbers.

Current Westlake home appraised value
$1,400,000
Outstanding mortgage balance
-$200,000
Estimated transaction costs (7%)
-$98,000
Net equity from sale
$1,102,000
Sun City Georgetown purchase (all cash)
-$600,000
Remaining cash available post-move
$502,000

Austin downsizing produces three distinct financial outcomes beyond the lifestyle change: substantial cash equity available for retirement savings or estate planning, a lower ongoing monthly carrying cost on the smaller home, and (for 65-plus owners) continued property tax ceiling benefits transferred to the new home. The specific amounts depend on the path chosen and the specific transaction coordination.

Not financial advice Specific numbers depend on individual circumstances. Transaction costs, mortgage balances, bridge-loan terms, and tax implications vary. Consult a CPA, financial planner, and real estate attorney as appropriate for your specific situation. Luke Allen is a Texas-licensed Realtor, not a financial advisor.

How to pick the right path for your Austin downsize

Three questions determine the right path for any specific Austin downsizer. First: how much equity is in the current home and how much mortgage remains? Downsizers with substantial equity and little or no mortgage have more path options including bridge financing. Downsizers with higher mortgage balances relative to equity are typically pushed toward Path 1 (sell first) because bridge financing becomes expensive relative to the equity available.

Second: how much timing flexibility do you have? Downsizers with flexible timing (no job tie, no family event forcing a specific date, no health timeline) can run any path. Downsizers with specific timing constraints often need Path 2 (buy first with bridge) or Path 3 (concurrent close) to hit the target date reliably.

Third: how risk-tolerant are you to the specific risks? Path 1 risk is 15-30 days of transitional living. Path 2 risk is bridge-loan carrying cost plus market risk on the current-home sale. Path 3 risk is coordination failure causing cascade delay. Path 4 risk is weak competitive position limiting new-home choices.

Direct contact

Luke Allen: [email protected] or 254-718-2567. Luke represents Austin downsizers on both the sell-side (listing the current home) and the buy-side (new home search) with coordinated timing across both. First conversation covers path selection, equity position, and target downsize home or community.
Downsizing FAQ

Common Austin downsizing questions

What is the best way to downsize in Austin without ending up in short-term housing?

Four paths. Path 1 (sell first, buy second) is cheapest but typically requires transitional housing. Path 2 (buy first with bridge financing) avoids short-term housing but adds bridge cost. Path 3 (concurrent close) coordinates both closings on same day. Path 4 (contingent purchase) ties them together structurally but weakens offer competitiveness.

What is bridge financing and how does it help Austin downsizers?

Short-term loan using current-home equity as collateral to fund the new-home purchase before the old home sells. Enables buying the new home at a comfortable pace, moving, then selling the old home from a non-pressured position. Typically 6-12 month term, interest-only, payoff at old-home closing. Works best for downsizers with low or no mortgage on current home.

What is the equity rollover math for a typical Austin downsize?

Example: $1.4M current home with $200K mortgage, $1.1M net equity after 7-8% transaction costs. Downsizing to $600K Sun City Georgetown property all cash: $502K remaining for retirement savings, home improvements, estate planning, or supplemental income. Specific numbers vary significantly by current home value, mortgage balance, target downsize.

How long does an Austin downsize typically take from decision to move-in?

Path 1 (sell first): 90-150 days. Path 2 (buy first with bridge): 60-120 days. Path 3 (concurrent close): 60-90 days with coordinated timing. Path 4 (contingent): 90-180 days depending on multiple-offer dynamics.

Who should I contact for an Austin downsizing conversation?

Luke Allen (TREC #788149) represents Austin downsizers on both sides with coordinated timing. First conversation covers path selection, equity position, target downsize home or community, timing. Contact: [email protected] or 254-718-2567.

Pick the right path

Current home equity, target downsize home or community, timing constraints, risk tolerance. Luke runs the path analysis and represents both sides of the move.

About the Author
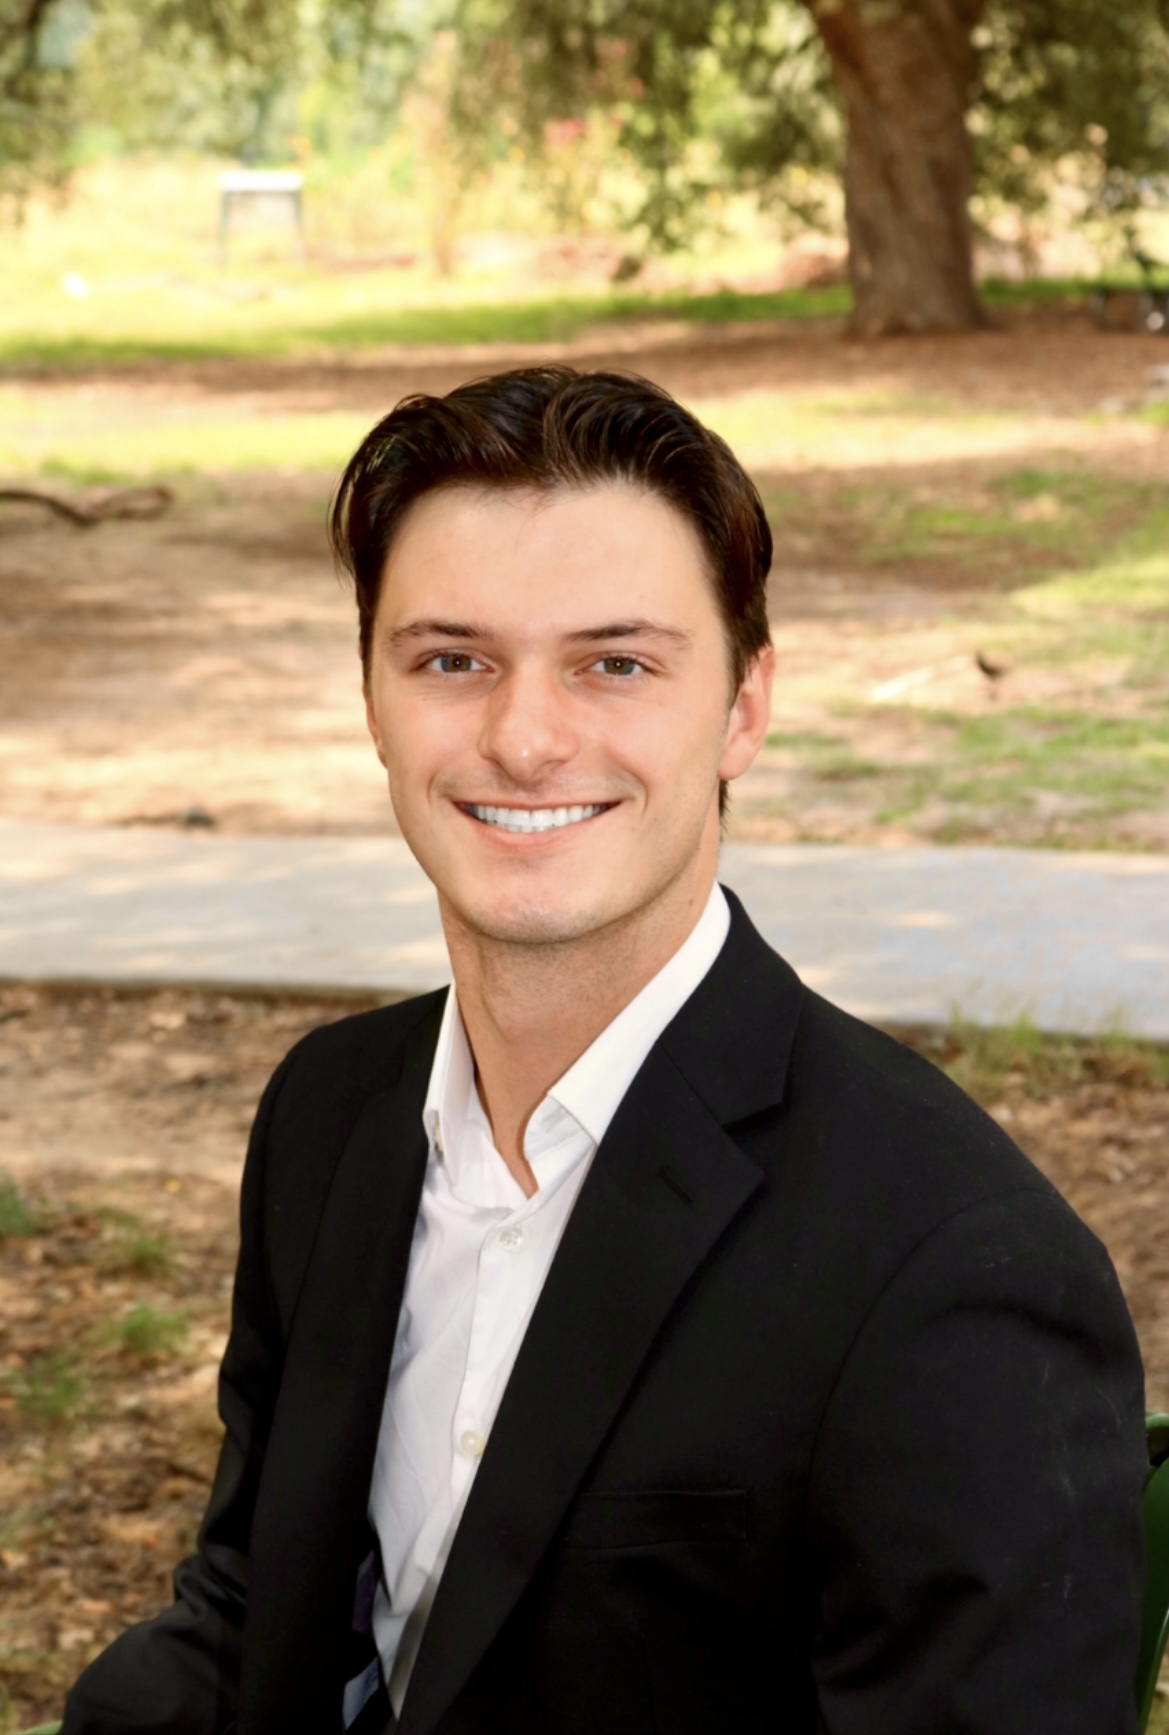
Luke Allen, Austin TX Realtor, TREC #788149
Luke Allen
Licensed Austin TX Realtor · TREC #788149 · Full-time since 2019
★★★★★ 5.0 on Google · 30 Reviews

Luke Allen is a full-time Austin TX Realtor with the Austin Marketing + Development Group brokerage. He works with buyers, sellers, and investors across every Austin ISD and the surrounding neighborhoods, from Downtown and East Austin to Round Rock, Cedar Park, and the Hill Country. Every page on this site is written and maintained by Luke. This page was last updated on October 12, 2026.

📞 (254) 718-2567 [email protected] More about Luke →